Godrej Brookstead Estate Payment Plan
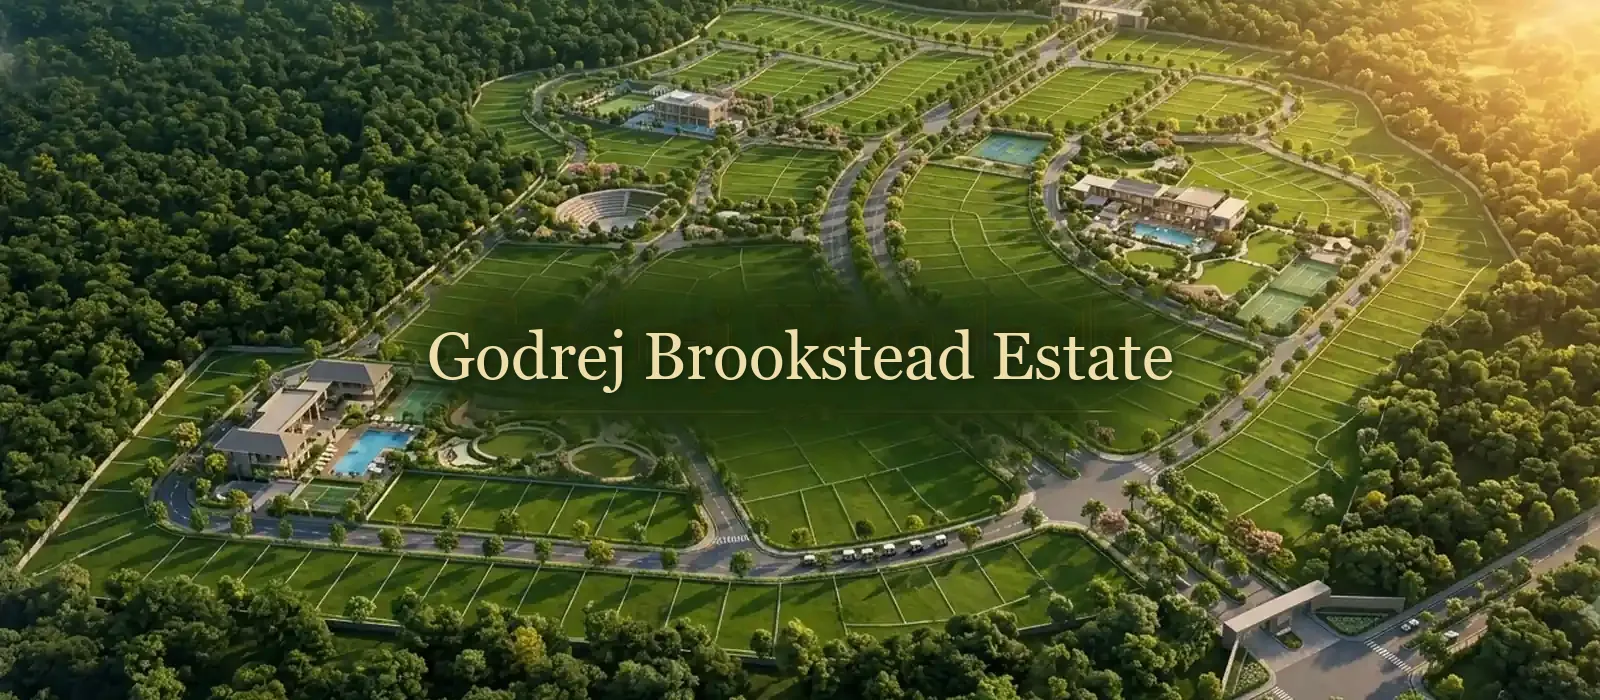
Featured Image of Godrej Brookstead Estate Payment Plan


Godrej Brookstead Estate payment plan spreads your plot cost across clear stages, from booking to the final payment. The exact schedule comes with your cost sheet at booking, and plotted projects usually link payments to layout milestones. This helps you plan your savings and bank loan around plots priced from ₹38.99 Lakhs to ₹1.23 Crore.

A good payment plan matters as much as the plot price. It decides how much cash you need upfront and when your loan starts. This guide explains how plot payment plans work, which stages to expect and how to plan your funds.
Plot Prices You Will Plan Around


Plot Type Plot Area Price
Cottage Plot 750 sq.ft. ₹38.99 Lakhs
Villa Plot 1,000 sq.ft. ₹49.99 Lakhs
Bungalow Plot 1,200 sq.ft. ₹60.49 Lakhs
Mansion Plot 1,500 sq.ft. ₹75.99 Lakhs
Estate Plot 1,646 to 2,400 sq.ft. ₹83.99 Lakhs to ₹1.23 Crore

How Payment Plans Work in Plotted Projects


In a plotted project, the developer builds roads, drains, water lines, power lines, parks and the clubhouse. Payment stages usually follow this work. You pay a part at booking, a part at agreement and the rest as the layout takes shape.

Under RERA rules, a promoter cannot take more than 10% of the plot cost before a registered agreement for sale. This protects you from paying a large sum before your rights are on paper.

Common Stages in a Plot Payment Schedule


Most branded plotted projects follow a pattern close to the one below. Your exact Brookstead schedule comes with the cost sheet at booking.

Stage What Happens What You Pay
Booking You select your plot and pay the booking amount Booking amount
Agreement You sign the agreement for sale Balance of the first instalment, up to 10% in total
Layout milestones Roads, drains, utilities and the clubhouse progress Instalments linked to each milestone
Completion The layout is ready for handover Final instalment
Registration The sale deed is registered Stamp duty and registration charges

This structure keeps your payments tied to real work on the ground. You can track each milestone before the next demand letter arrives.

Types of Payment Plans You May See


Developers use a few common plan types. Ask the sales team which options apply at launch.

Milestone linked plan: payments follow work stages on site. It is the most common plan for plots and gives you the best link between money and progress.

Down payment plan: you pay a large share upfront, often in return for a lower rate. It suits buyers with ready funds.

Flexi plan: a mix of upfront and milestone payments. It suits buyers who want a balance between price and cash flow.

Subvention or deferred plans: in some launches, the developer bears part of the loan interest for a set time. Read the terms closely, since these plans can carry a higher base price.

Planning Your Funds for Each Stage


Plan your money in two buckets: your own contribution and the bank loan.

Your own contribution covers the booking amount and any share the bank does not fund. Banks usually fund a smaller share of the price for plots than for ready homes. So keep a larger down payment ready than you would for a flat.

You also need cash for stamp duty and registration at the time of the sale deed. In Tamil Nadu, stamp duty is 7% and the registration fee is 4%. On the Cottage Plot at ₹38.99 Lakhs, that adds about ₹4.29 Lakhs if charged on the sale price.

Using a Bank Loan With the Payment Plan


Most banks offer plot loans for residential plots in approved layouts. Many also offer composite loans that cover the plot now and your house later.

  • Get your loan sanction early, before the agreement stage.
  • Match loan disbursements to the milestone schedule in your agreement.
  • Check whether the bank has approved the project, since that speeds up processing.
  • Keep the demand letters and receipts for every payment you make.

RBI raised the repo rate to 5.50% on 7 October 2026. With a floating rate loan, your EMI can move at each reset. So keep a buffer in your monthly budget.

Smart Checks Before You Accept a Payment Plan


  • Confirm the booking amount and whether it is refundable.
  • Make sure no more than 10% is taken before the registered agreement.
  • Check that every instalment links to a clear milestone.
  • Read the penalty terms for late payments on both sides.
  • Ask whether GST applies to any separately charged item, such as club fees.
  • Pay only through bank transfers to the official project account.

FAQs


1. What is the payment plan for Godrej Brookstead Estate?

The Godrej Brookstead Estate payment plan comes with your cost sheet at booking. Plotted projects like this usually start with a booking amount and then link instalments to layout work. The balance is paid at completion and registration.

2. How much is the booking amount at Godrej Brookstead Estate?

The booking amount is shared by the sales team at launch with the cost sheet. Under RERA, a promoter cannot collect over 10% of the plot cost before a registered agreement.

3. Can I get a bank loan for a Godrej Brookstead Estate plot?

Yes. Most banks offer plot loans and composite loans for residential plots in approved layouts. Banks fund a smaller share for plots than for homes, so plan a larger down payment.

4. When do I pay stamp duty and registration charges?

You pay stamp duty and registration charges when the sale deed is registered. In Tamil Nadu, stamp duty is 7% and the registration fee is 4%. They are charged on the guideline value or sale value, whichever is higher.

5. Is there a subvention or no EMI plan at Godrej Brookstead Estate?

Launch phase plans are shared at the time of launch in December 2026. If a subvention plan is offered, compare its base price with the regular plan. Read the interest terms closely before you choose.

6. Can NRIs follow the same payment plan?

Yes. NRIs follow the same payment stages as resident buyers. They must pay through NRE, NRO or FCNR accounts or through normal banking channels. Cash or foreign currency notes are not allowed.

Enquiry
Enquire Now